In this act Annex II of 4
- 1Definitions
- 2Calculation of the total value of assets under management
- 3Ongoing monitoring of assets under management
- 4Occasional breach of the threshold
- 5Information to be provided as part of registration
- 6General provisions on the calculation of leverage
- 7Gross method for calculating the exposure of the AIF
- 8Commitment method for calculating the exposure of an AIF
- 9Methods of increasing the exposure of an AIF
- 10Conversion methodologies for derivative instruments
- 11Duration netting rules
- 12Professional liability risks
- 13Qualitative requirements addressing professional liability risks
- 14Additional own funds
- 15Professional indemnity insurance
- 16General obligations for competent authorities
- 17Duty to act in the best interests of the AIF or the investors in the AIF and the integrity of the market
- 18Due diligence
- 19Due diligence when investing in assets of limited liquidity
- 20Due diligence in the selection and appointment of counterparties and prime brokers
- 21Acting honestly, fairly and with due skills
- 22Resources
- 23Fair treatment of investors in the AIF
- 24Inducements
- 25Effective employment of resources and procedures — handling of orders
- 26Reporting obligations in respect of execution of subscription and redemption orders
- 27Execution of decisions to deal on behalf of the managed AIF
- 28Placing orders to deal on behalf of AIFs with other entities for execution
- 29Aggregation and allocation of trading orders
- 30Types of conflicts of interest
- 31Conflicts of interest policy
- 32Conflicts of interest related to the redemption of investments
- 33Procedures and measures preventing or managing conflicts of interest
- 34Managing conflicts of interest
- 35Monitoring conflicts of interest
- 36Disclosure of conflicts of interest
- 37Strategies for the exercise of voting rights
- 38Risk management systems
- 39Permanent risk management function
- 40Risk management policy
- 41Assessment, monitoring and review of the risk management systems
- 42Functional and hierarchical separation of the risk management function
- 43Safeguards against conflicts of interest
- 44Risk limits
- 45Risk measurement and management
- 46Liquidity management system and procedures
- 47Monitoring and managing liquidity risk
- 48Liquidity management limits and stress tests
- 49Alignment of investment strategy, liquidity profile and redemption policy
- 50Definitions
- 51Requirements for retained interest
- 52Qualitative requirements concerning sponsors and originators
- 53Qualitative requirements concerning AIFMs exposed to securitisations
- 54Corrective action
- 55Grandfathering clause
- 56Interpretation
- 57General requirements
- 58Electronic data processing
- 59Accounting procedures
- 60Control by the governing body, senior management and supervisory function
- 61Permanent compliance function
- 62Permanent internal audit function
- 63Personal transactions
- 64Recording of portfolio transactions
- 65Recording of subscription and redemption orders
- 66Recordkeeping requirements
- 67Policies and procedures for the valuation of the assets of the AIF
- 68Use of models to value assets
- 69Consistent application of valuation policies and procedures
- 70Periodic review of valuation policies and procedures
- 71Review of individual values of assets
- 72Calculation of the net asset value per unit or share
- 73Professional guarantees
- 74Frequency of valuation of assets held by open-ended AIFs
- 75General principles
- 76Objective reasons for delegation
- 77Features of the delegate
- 78Delegation of portfolio or risk management
- 79Effective supervision
- 80Conflicts of interest
- 81Consent and notification of sub-delegation
- 82Letter-box entity and AIFM no longer considered to be managing an AIF
- 83Contractual particulars
- 84Criteria for assessing prudential regulation and supervision applicable to a depositary in a third country
- 85Cash monitoring — general requirements
- 86Monitoring of the AIF’s cash flows
- 87Duties regarding subscriptions
- 88Financial instruments to be held in custody
- 89Safekeeping duties with regard to assets held in custody
- 90Safekeeping duties regarding ownership verification and record keeping
- 91Reporting obligations for prime brokers
- 92Oversight duties — general requirements
- 93Duties regarding subscription and redemptions
- 94Duties regarding the valuation of shares/units
- 95Duties regarding the carrying out of the AIFM’s instructions
- 96Duties regarding the timely settlement of transactions
- 97Duties related to the AIF’s income distribution
- 98Due diligence
- 99Segregation obligation
- 100Loss of a financial instrument held in custody
- 101Liability discharge under Article 21(12) of Directive 2011/61/EU
- 102Objective reasons for the depositary to contract a discharge of liability
- 103General principles for the annual report
- 104Content and format of the balance sheet or statement of assets and liabilities and of the income and expenditure account
- 105Report on the activities of the financial year
- 106Material changes
- 107Remuneration disclosure
- 108Periodic disclosure to investors
- 109Regular disclosure to investors
- 110Reporting to competent authorities
- 111Use of leverage on a ‘substantial basis’
- 112Restrictions on the management of AIFs
- 113General requirements
- 114Mechanisms, instruments and procedures
- 115Data protection
- 116Exchange of information on the potential systemic consequences of AIFM activity
- 117Entry into force
- Annex I
- Annex II
- Annex III
- Annex IV
Annex II
Financial servicesLevel 2Delegated RegulationAIFMDIn forceIn force on the date shown, by the dates in the Official Journal.
Conversion methodologies for derivative instruments
1. The following conversion methods shall be applied to the non-exhaustive list below of standard derivatives:
(a) Futures
— Bond future : Number of contracts * notional contract size * market price of the cheapest-to-deliver reference bond
— Interest rate future : Number of contracts * notional contract size
— Currency future : Number of contracts * notional contract size
— Equity future : Number of contracts * notional contract size * market price of underlying equity share
— Index futures : Number of contracts * notional contract size * index level
(b) Plain vanilla options (bought/sold puts and calls)
— Plain vanilla bond option : Notional contract value * market value of underlying reference bond * delta
— Plain vanilla equity option : Number of contracts * notional contract size* market value of underlying equity share * delta
— Plain vanilla interest rate option : Notional contract value * delta
— Plain vanilla currency option : Notional contract value of currency leg(s) * delta
— Plain vanilla index options : Number of contracts * notional contract size * index level * delta
— Plain vanilla options on futures : Number of contracts * notional contract size * market value of underlying asset * delta
— Plain vanilla swaptions : Reference swap commitment conversion amount * delta
— Warrants and rights : Number of shares/bonds * market value of underlying referenced instrument * delta
(c) Swaps
— Plain vanilla fixed/floating rate interest rate and inflation swaps : notional contract value
— Currency swaps : Notional value of currency leg(s)
— Cross currency interest rate swaps : Notional value of currency leg(s)
— Basic total return swap : Underlying market value of reference asset(s)
— Non-basic total return swap : Cumulative underlying market value of both legs of the TRS
— Single name credit default swap : Protection seller — The higher of the market value of the underlying reference asset or the notional value of the Credit Default Swap. Protection buyer — Market value of the underlying reference asset
— Contract for differences : Number of shares/bonds * market value of underlying referenced instrument
(d) Forwards
— FX forward : notional value of currency leg(s)
— Forward rate agreement : notional value
(e) Leveraged exposure to indices with embedded leverage
A derivative providing leveraged exposure to an underlying index, or indices that embed leveraged exposure to their portfolio, must apply the standard applicable commitment approach to the assets in question.
2. The following conversion methods shall be applied to the non-exhaustive list below of financial instruments which embed derivatives:
— Convertible bonds : Number of referenced shares * market value of underlying referenced shares * delta
— Credit linked notes : Market value of underlying reference asset(s)
— Partly paid securities : Number of shares/bonds * market value of underlying referenced instruments
— Warrants and rights : Number of shares/bonds * market value of underlying referenced instrument * delta
3. List of examples of non-standard derivatives with the related commitment methodology being used:
— Variance swaps: Variance swaps are contracts that allow investors to gain exposure to the variance (squared volatility) of an underlying asset and, in particular, to trade future realised (or historical) volatility against current implied volatility. According to market practice, the strike and the variance notional are expressed in terms of volatility. For the variance notional, this gives:
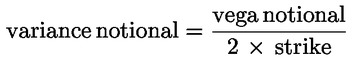
The vega notional provides a theoretical measure of the profit or loss resulting from a 1 % change in volatility.
As realised volatility cannot be less than zero, a long swap position has a known maximum loss. The maximum loss on a short swap is often limited by the inclusion of a cap on volatility. However without a cap, a short swap’s potential losses are unlimited.
The conversion methodology to be used for a given contract at time t is:
Variance notional * (current) variancet (without volatility cap)
Variance notional * min [(current) variancet volatility cap2] (with volatility cap)
whereby: (current) variancet is a function of the squared realised and implied volatility, more precisely:
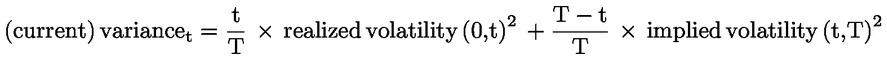
— Volatility swaps
By analogy with the variance swaps, the following conversion formulae should be applied to volatility swaps:
— Vega notional * (current) volatilityt (without volatility cap)
— Vega notional * min [(current) volatilityt; volatility cap] (with volatility cap)
whereby the (current) volatility t is a function of the realised and implied volatility.
4. Barrier (knock-in knock-out) options
Number of contracts * notional contract size * market value of underlying equity share * delta
Full document 117 articles and 4 annexes on one page