<!-- headlesslaw {"release":{"id":"77efe5c3ee85cad86882678e1111183cf251ec495e79957d761287107e77d7ee","published":"2026-11-18T22:19:40Z","pinned":false},"limits":{"coverage":{"history":"full","held_since":"2013-03-22","gaps":[],"covered":["231/2013 L2"],"not_covered":["national guidance","court decisions"]},"freshness":{"release_id":"77efe5c3ee85cad86882678e1111183cf251ec495e79957d761287107e77d7ee","release_published":"2026-11-18T22:19:40Z","checked_at":"2026-11-17","checked_against":"EUR-Lex"},"truncation":null,"failures":[],"incomplete":[]},"page":{"path":"/aifmd/level-2/32013r0231/annexes/annex-iii","url":"https://www.headlesslaw.com/aifmd/level-2/32013r0231/annexes/annex-iii","title":"Annex III","family":"l2_unit_view","work_id":"spaces/aifmd/level-2/32013r0231","view_of":"/aifmd/level-2/32013r0231","status":"in_force","force_status":"in_force","date_state":"current","requested_date":null,"as_of":"2026-11-19","applies_from":null,"application":null,"version_label":"Consolidated version of 12 February 2024","check":{"against":"EUR-Lex","on":"2026-11-17"},"check_result":"matched","official_url":"https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:02013R0231-20240212","valid_from":"2024-02-12","valid_until":null,"revision":1,"content_id":"ea2350420b8c93b8","versions":["2024-02-12"],"version_url":"https://www.headlesslaw.com/aifmd/level-2/32013r0231/annexes/annex-iii/versions/2024-02-12","revision_url":"https://www.headlesslaw.com/aifmd/level-2/32013r0231/annexes/annex-iii/versions/2024-02-12/rev/ea2350420b8c93b8","versions_url":"https://www.headlesslaw.com/aifmd/level-2/32013r0231/annexes/annex-iii/versions","relations_url":"https://www.headlesslaw.com/aifmd/level-2/32013r0231/annexes/annex-iii/relations","act_url":"https://www.headlesslaw.com/aifmd/level-2/32013r0231#annex-iii","source_line":"Commission Delegated Regulation (EU) No 231/2013 · binding · OJ L 83, 22.3.2013 · dated 19 Dec 2012 [in force]","attribution":{"prepared_by":"European Commission","published_by":"Publications Office of the EU","published_in":"Official Journal of the European Union","document_type":"delegated_regulation","legal_nature":"binding_adopted","addressees":"not stated in the document","dates":{"document_date":"2012-12-19","entry_into_force":"2013-04-11","locators":{"document_date":"CELLAR 32013R0231 work_date_document","entry_into_force":"CELLAR 32013R0231 resource_legal_date_entry-into-force (earliest on or after the document date)"}},"adoption":null},"context":{"act":{"work_id":"spaces/aifmd/level-2/32013r0231","path":"/aifmd/level-2/32013r0231","name":"Commission Delegated Regulation (EU) No 231/2013","number":"231/2013","celex":"32013R0231","title_official":null,"document_date":"2012-12-19"},"position":{"kind":"annex","key":"annex-iii","index":3,"articles":117,"annexes":4},"prev":{"path":"/aifmd/level-2/32013r0231/annexes/annex-ii","key":"annex-ii","title":"Annex II"},"next":{"path":"/aifmd/level-2/32013r0231/annexes/annex-iv","key":"annex-iv","title":"Annex IV"},"act_anchor":"#annex-iii"}}} -->
# Annex III

**Commission Delegated Regulation (EU) No 231/2013 · binding · OJ L 83, 22.3.2013 · dated 19 Dec 2012 [in force]**

*In force · Consolidated version of 12 February 2024 · Verified 17 Nov 2026 · [Official source](https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:02013R0231-20240212)*

### Duration netting rules

**1.** An interest rate derivative shall be converted into its equivalent underlying asset position in accordance with the following methodology:

The equivalent underlying asset position of each interest rate derivative instrument shall be calculated as its duration divided by the target duration of the AIF and multiplied by the equivalent underlying asset position:
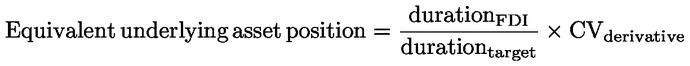
![image](https://www.headlesslaw.com/images/sha256/ea25fea3722be75bdba06298050381f432575ac7ae4a64da8f8b5039afc19d49)

where:

**—** duration <sub>FDI</sub> is the duration (sensitivity of the market value of the financial derivative instrument to interest rate movements) of the interest rate derivative instrument,

**—** duration <sub>target</sub> is in line with the investment strategy, the directional positions and the expected level of risk at any time and will be regularised otherwise. It is also in line with the portfolio duration under normal market conditions,

**—** CV<sub>derivative</sub> is the converted value of the derivative position as defined by the Annex II.

**2.** The equivalent underlying asset positions calculated in accordance with to paragraph 1 shall be netted as follows:

**(a)** Each interest rate derivative instrument shall be allocated to the appropriate maturity range of the following maturity-based ladder:

Maturities ranges

**1.** 0-2 years

**2.** 2-7 years

**3.** 7-15 years

**4.** > 15 years

**(b)** The long and short equivalent underlying asset positions shall be netted within each maturity range. The amount of the former which is netted with the latter is the netted amount for that maturity range.

**(c)** Starting with the shortest maturity range, the netted amounts between two adjoining maturity ranges shall be calculated by netting the amount of the remaining unnetted long (or short) position in the maturity range (i) with the amount of the remaining unnetted short (long) position in the maturity range (i + 1).

**(d)** Starting with the shortest maturity range, the netted amounts between two remote maturity ranges separated by another one shall be calculated by netting the amount of the remaining unnetted long (or short) position in the maturity range (i) with the amount of the remaining unnetted short (long) position in the maturity range (i + 2).

**(e)** The netted amount shall be calculated between the remaining unnetted long and short positions of the two most remote maturity ranges.

**3.** The AIF shall calculate its exposures as the sum of absolute values:

**—** 0 % of the netted amount for each maturity range,

**—** 40 % of the netted amounts between two adjoining maturity ranges (i) and (i + 1),

**—** 75 % of the netted amounts between two remote maturity ranges separated by another one, meaning maturity ranges (i) and (i + 2),

**—** 100 % of the netted amounts between the two most remote maturity ranges, and

**—** 100 % of the remaining unnetted positions.
